All Categories
Featured


Reviewing California Medicare Insurance Plans for 2026
Table of Contents
If your income is, you will likely for those temporary subsidies and pay the full expense of your insurance. So, in spite of headlines suggesting subsidies are "disappearing," that's not the complete story. They're just and the shift will disproportionately impact those simply above that income limit. Losing aid support is simply one side of the equation.
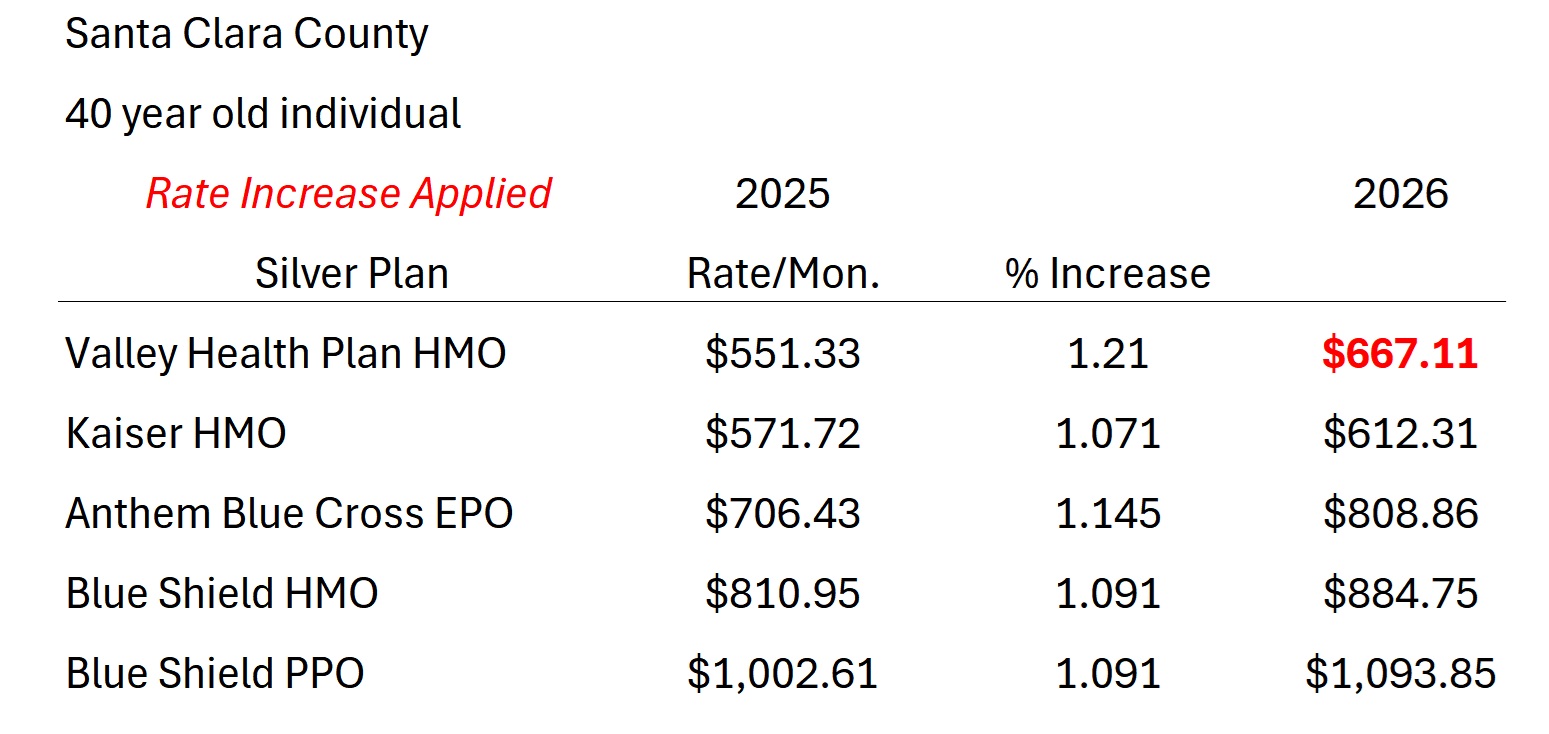
Covered California has actually already predicted an statewidethe largest given that the exchange released. Historically, rate modifications hover around 5%, so this is roughly. Nationwide, experts anticipate even steeper jumps. Some states are bracing for, driven by inflation, increasing medical expenses, and continued unpredictability in the healthcare market. Insurance coverage companiesoften painted as the bad guys in these conversationsare dealing with installing claims costs, restricted revenue margins under ACA policies, and greater monetary danger overall.
If your home income is above 400% FPL, you might see in 2026. Lots of Californians in this classification will have to reassess their coverage levelpossibly moving from down to simply to stay insured. Some might consider dropping coverage altogether, but that's a hazardous move. Medical insurance still secures you from and shields your possessions in the event of a severe health problem or accident.
Now more than ever, it's crucial to examine your plan, understand your options, and make clever changes before starts. At, our objective is basic: to help Californians stay insured, informed, and protectedwithout charging a single dollar for our services. Our certified representatives work with throughout the state, offering customized assistance to help you: Compare plans and providers side-by-side Understand how your earnings affects your premiums Explore subsidy options and eligibility Change coverage to fit your changing budget Keep the doctors and health centers you rely on Open Enrollment for 2026 coverage starts, however present Covered California members can.
Yes, health care expenses are climbing up, and 2026 will bring brand-new difficulties. If you 'd like individually assistance reviewing your options for 2026, our group is ready.
Reviewing SoCal Health Advantage Options Today
Together, we'll ensure you remain protectedno matter what the marketplace does next. Yes if your, you'll still receive premium aids in 2026. The recent expansion that enabled those above 400% FPL to receive financial support will end after 2025, meaning higher-income homes might pay complete rate for coverage.
Some counties and plans might see even bigger jumps depending upon carrier, region, and age. Reviewing your plan early throughout can assist you minimize the effect of these boosts. There are several techniques to help offset greater premiums: (Bronze, Silver, Gold, Platinum) to discover the most affordable prepare for your requirements.
at Medical Insurance Coverage Today for a free, tailored review. Our experts can recognize protection adjustments that preserve security while lowering your month-to-month cost.
If you attempted to purchase or restore home insurance in California over the last few years, you probably faced the same wall a lot of property owners did: your routine insurer non-renewed you, a brand-new provider would not estimate your postal code at all, and you ended up on the state's FAIR Plan typically paying more for less coverage than a basic policy would offer you.
Here's where things actually stand in 2026, and what it suggests if you're currently on the FAIR Plan or were denied in the past. Back-to-back wildfire seasons, capped by the Palisades and Eaton fires in January 2025, removed tens of billions of dollars in insured value in a matter of weeks.
Comparing California Medicare Advantage Plans for 2026
The FAIR Plan produced as a last-resort backstop, not a daily insurance coverage choice absorbed the overflow, growing from a few hundred thousand policies a few years ago to well over half a million today. California's Department of Insurance coverage presented a bundle of reforms understood as the Sustainable Insurance Coverage Method, which provides insurance providers more flexibility on rates in exchange for a dedication to write more policies in the ZIP codes the FAIR Plan had actually been forced to take in.
State Farm General and Allstate 2 of the biggest names in the state have actually stayed largely closed to brand-new property owners service through 2026, so "the market is recovery" doesn't imply every carrier is open, and it doesn't imply every ZIP code certifies. Even as the personal market opens back up in some areas, FAIR Plan premiums have actually continued climbing up filings in 2026 have actually pushed rates up by roughly 30% or more in numerous areas, with the exact effect varying a lot by postal code.

Latest Posts
Exploring New CA Market Trends

Crucial California Insurance Market Updates in 2026

Top Strategies for Optimizing Local California Plan Benefits